Blog

  • Bank Card Declined? Gift Cards, PayPal or a Virtual Card

    Bank Card Declined? Gift Cards, PayPal or a Virtual Card

    Example scenario: your music streaming renewal fails. You try again and get “Your card was declined”. Your bank says the card is fine but flags foreign online charges as risky, and the person on the phone cannot promise it will not happen next month. The subscription pauses in three days. You start searching for another way to pay and find three suggestions everywhere: buy a gift card, use PayPal, or get a virtual card.

    Each of these alternative payment methods for subscriptions works in some situations and fails in others. This guide compares them honestly, starting with the fix most people skip, and ends with a framework for choosing the right one for each service you pay for.

    First, try to fix the bank card

    Before adding a new payment method, rule out the simple causes. Many declines come from settings you can change in minutes:

    1. Check the card’s online and international settings in your banking app. Many banks let you switch foreign online payments on and off.
    2. Check your limits. Daily or per-transaction online limits can block a renewal.
    3. Confirm the billing address on the subscription matches the address your bank holds.
    4. Approve the 3D Secure prompt if your bank sends one. A missed prompt looks like a decline.
    5. Ask the bank directly why the charge was blocked and whether it will recur.

    If none of that works, or your bank blocks foreign subscriptions as policy, it is time for an alternative.

    Option 1: app store billing with gift cards

    Many subscriptions can be paid through the Apple App Store or Google Play instead of directly. You redeem a gift card into your account balance, and the store bills the subscription from that balance.

    What works well: no bank card needed for the balance itself, gift cards are sold in shops in many countries, and the store handles cancellations in one place.

    What to watch: not every subscription is available through the stores, and not every subscription can be charged to a balance. Apple’s page on what an Apple Account balance can pay for says some subscriptions cannot be charged to the balance, that an ongoing subscription is charged to the balance only if the balance covers the whole charge and another valid payment method is on file, and that some purchases may require a card on file. Google Play also accepts its balance and gift cards for many purchases, with similar limits. Gift cards are tied to the country of your account, and store prices can be higher than paying the service directly.

    Safety note: buy gift cards only from official retailers, and never pay anyone who asks you to settle a bill with gift card codes. That is a common scam pattern.

    Option 2: the service’s own gift cards

    Some streaming and gaming services sell their own gift cards that you redeem directly into your account. Where available, this is one of the simplest options.

    What works well: no card on file and no surprise renewals once the credit runs out.

    What to watch: only some services sell them, they are usually limited to the country where they were bought, and you need to buy a new one before the credit ends. Using gift cards bought for another region to get a different price can break the service’s terms.

    Option 3: PayPal

    PayPal sits between you and the merchant. You set up an automatic payment (PayPal also calls it a billing agreement or subscription), and PayPal charges the funding source you choose for that merchant.

    What works well: the merchant never sees your card number, you can manage and cancel automatic payments in one place, and you can switch the funding source without updating the merchant.

    What to watch: the merchant must accept PayPal, which many do but not all. PayPal still needs a funding source in most cases, such as a linked card or bank account or a PayPal balance, so if your card is blocked for foreign charges, PayPal may hit the same block. Currency conversion by PayPal can add cost, and PayPal’s features differ by country.

    Option 4: a virtual card

    A virtual card is a card number you can enter wherever cards are accepted. It can come from your own bank, from a multi-currency account such as Wise or Revolut, or from a prepaid card provider.

    What works well: works on any checkout that takes card payments, keeps your main card off subscription sites, and a prepaid card cannot be charged more than its balance, which caps forgotten renewals.

    What to watch: some merchants decline prepaid cards, a prepaid balance must be topped up before renewal day, and you should match the card’s currency to the merchant to avoid conversion on each charge.

    Side-by-side comparison

    MethodWorks forNeedsMain advantageMain drawback
    Fixing the bank cardAny serviceYour bank’s cooperationNo new accountBank policy may not change
    App store gift cardsSubscriptions sold through the storeGift card for your account’s countryNo card needed for the balanceLimited to store subscriptions; some need a card on file
    Service gift cardsServices that sell themGift card from the same countryNo renewal surprisesFew services offer them
    PayPalMerchants that accept PayPalA funding source in most casesCard number hidden; easy to cancelFunding card may still be blocked
    Prepaid virtual cardCard checkouts that accept prepaidA provider and a way to fund itWorks like a card; capped balanceSome merchants decline prepaid cards

    A decision framework

    1. Is the subscription sold through Apple or Google? If yes, store billing with a gift card balance is a low-effort option, as long as the subscription can be charged to a balance.
    2. Does the service sell its own gift cards in your country? If yes, that avoids recurring card charges entirely.
    3. Does the merchant accept PayPal, and will your funding source work? If both are true, PayPal adds a layer of privacy and control.
    4. None of the above? A virtual card is the most general fallback because it works wherever cards do. Check the merchant accepts prepaid cards before you buy one.

    Example: a crypto-funded virtual card from Vizovcc

    For people whose bank card keeps failing on foreign subscriptions and who already hold crypto, Vizovcc is one example of the virtual card route. It sells prepaid virtual cards that you buy from an account balance funded with Bitcoin, USDT, USDC, ETH or other coins. Signing up needs an email address, and no bank account is involved in funding it. Vizovcc’s page on prepaid cards you fund with crypto explains the steps.

    The card is a regular prepaid card once it is issued: it spends its loaded balance, not your coins directly. Card pages show the price and how it splits between the issue charge and the spendable balance. Details appear in the dashboard once the card is ready, often within minutes. Each card has its own balance and can be frozen and unfrozen, cards support 3D Secure, and the catalog includes USD and local-currency cards. The site lists uses such as Netflix, Spotify and YouTube Premium.

    The limits are worth stating plainly. Vizovcc is funded with crypto only. Each platform decides which cards it accepts and any merchant can decline a prepaid card, so test with one subscription first. Card purchases are final, so choose the card and currency carefully. And a card is a payment method, not a way around a service’s country pricing or terms.

    FAQ

    Can I pay Netflix or Spotify without a bank card?

    Often, yes, through gift cards where the service sells them, through app store billing where offered, or with a virtual card the service accepts. Options vary by country.

    Is PayPal safer than entering my card?

    It hides your card number from the merchant and makes cancelling easier. Your funding source is still charged, so keep it secure.

    Why does my subscription still need a card on file with a gift card balance?

    Some stores require a backup payment method for recurring charges in case the balance runs short. Apple states this for ongoing subscriptions.

    Key takeaways

    • Try fixing the bank card first: settings, limits, address and 3D Secure.
    • Gift cards work best for app store subscriptions and services that sell their own cards.
    • PayPal adds privacy and control but usually depends on a funding source that may also be blocked.
    • A prepaid virtual card is the most general fallback, as long as the merchant accepts prepaid cards.

    Pick the subscription that fails most often and work through the framework above for that one service. If a crypto-funded prepaid card is the right fit, compare the options at Vizovcc and test one card before moving other subscriptions.

  • Virtual vs Physical Business Cards: Security, Control, Cost

    Virtual vs Physical Business Cards: Security, Control, Cost

    Here is a scenario many small businesses will recognize (an example, not a real case). The office manager’s company card is in a coat pocket on a train, and it does not come home. By the time anyone notices, the card has been reported, the bank has cancelled it, and a replacement is in the mail. Then the real cost shows up: the same card number was saved on the website host, the accounting software, two ad accounts and a design tool. Each one now fails at renewal, and someone spends the next week updating payment details one vendor at a time.

    Losing a card is the obvious risk. The bigger problem is that one card number was doing every job in the business. That is the core of the virtual vs physical business cards question. It is less about plastic versus pixels and more about how many places a single card number lives, and how much damage follows when that number is exposed. This guide compares both card types on security, control and cost, and gives you a simple way to decide which spend belongs on which card.

    What separates a virtual card from a physical one

    A physical business card is the plastic card with a chip, a magnetic stripe and often a contactless antenna. It works in shops, at hotel desks, at fuel pumps and online. A virtual card is a card number, expiry date and security code that exists only in an app or dashboard. It is built for online and phone payments, which the card industry calls card-not-present transactions.

    Both run on the same card networks, such as Visa and Mastercard, so a merchant usually cannot tell the difference at checkout. The differences sit with the business that holds the card: how many numbers it can have, what each one is used for, and what happens when one is compromised.

    Security: where each card type is exposed

    Physical cards: theft, skimming and long-lived numbers

    A plastic card can be lost, stolen, photographed or skimmed at a tampered terminal. Its number is printed on it, so anyone who handles it can read the details. Most business teams also keep one physical card active for years and reuse the same number everywhere, which means a single leak can reach every vendor that card pays.

    Virtual cards: no plastic, but numbers still leak

    Virtual cards cannot be lost on a train or skimmed at a terminal, because there is nothing to touch. They are not immune to fraud. A virtual card number can still be exposed in a merchant data breach, a phishing page or a shared spreadsheet. The security advantage comes from how they are used: because virtual cards are easy to create, a business can give each vendor or project its own number. When one leaks, you replace that one card and the rest keep working.

    The real variable is blast radius

    Think of every card number as having a blast radius: the set of payments that break, and the money at risk, if that number is compromised. A physical card shared across a whole business has a wide blast radius. A virtual card dedicated to one software vendor has a small one. Card type matters, but how you assign cards matters more.

    Control: who can spend, where and how much

    Control is where the two types differ most in practice.

    • Number of cards. Physical cards take time to produce and ship, so most teams hold only a few. Virtual cards can usually be created from a dashboard, which makes one card per vendor, teammate or project realistic.
    • Who holds the details. A physical card has to be handed to someone. A virtual card can be added to a vendor account by one admin, so the person running the tool never sees the number.
    • Built-in controls. Some virtual card providers offer per-card spending limits, merchant locks, single-use numbers or a freeze button. These vary widely by provider, so check which ones a provider offers rather than assuming every virtual card has them.
    • Prepaid ceilings. A prepaid card, virtual or physical, cannot spend more than its loaded balance. That is a simple control that needs no settings at all.
    • Where it works. Physical cards win for in-person spend. Many hotels, car rental desks and fuel stations expect a card to be presented, and some virtual cards can only be used online.

    Cost: the line items people forget

    The sticker price of a card is rarely the full cost. When you compare options, count these:

    • Issue and replacement fees. Some providers charge per card, some charge nothing up front. Physical replacements also cost time while a new card is in the mail.
    • Monthly or annual fees. A fee that looks small on one card adds up if you plan to hold many cards.
    • Transaction and currency fees. Check the fee per payment and any foreign exchange charge, especially for tools that bill in another currency.
    • Admin time. Updating a compromised card on every vendor account is a cost, even if no money is stolen. So is reconciling a statement where every charge shares one number.
    • Failed renewals. A declined renewal can lock a team out of a tool until someone fixes the payment method.

    Virtual vs physical business cards at a glance

    FactorPhysical business cardVirtual business card
    Loss and theftCan be lost, stolen or skimmedNothing physical to lose
    Data breach exposureOne number often reused everywhereCan be limited to one vendor per number
    ReplacementNew plastic has to be produced and deliveredUsually a new number from a dashboard
    Number of cards a team holdsUsually a fewCan be one per vendor, teammate or project
    In-person spendWorks in shops, hotels and pumpsLimited, unless added to a mobile wallet where supported
    Online subscriptions and adsWorks, but mixes every charge on one statementStrong fit, with cleaner records per card
    Spending controlsSet by the bank, often account-wideVaries by provider, from none to detailed

    A decision framework: which spend goes on which card

    Most businesses end up using both. Walk through each type of spend with these steps:

    1. Ask whether the card must be presented in person. Travel, fuel, hotel deposits and in-store purchases usually belong on a physical card.
    2. Check whether the charge recurs. Subscriptions, hosting, software seats and ad accounts renew automatically. Give each recurring vendor its own virtual card so one problem never breaks the others.
    3. Estimate the blast radius. If a vendor stores card details and has a large customer base, a dedicated number limits what a breach could reach.
    4. Decide who needs to use it. If a teammate only needs a tool to work, add the card yourself as admin instead of sharing the number.
    5. Pick the ceiling. If you want a hard cap without configuring limits, a prepaid card with a set balance gives you one.
    6. Record it. Keep a simple register: last four digits, vendor, owner, renewal date and expiry.

    Example: the virtual column with ZenVCC

    ZenVCC is one example of a virtual-only option. It is a prepaid virtual card platform, not a bank, and it offers no credit line. You fund one balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), and each deposit is checked on its blockchain before it is credited. From that balance you buy prepaid Visa, Mastercard, American Express or Maestro cards, one per vendor, project or teammate.

    For the security and cost points above, the relevant details are:

    • Separate cards from one balance. Each tool or ad account can have its own card, so a leaked number affects only that card.
    • Prepaid ceiling. A card cannot spend more than what it holds, and there is no credit to run up.
    • Clear costs. A one-time $10 issue fee per card, $0.10 per card payment and no monthly fee, whether you hold one card or fifty.
    • Three-year validity. Cards stay valid for three years from the day they are ready, so renewals rarely break because of expiry.
    • Refunds on failed orders. If a card cannot be prepared, the full amount, including the issue fee, returns to your balance.

    The limits matter just as much. ZenVCC issues no physical cards, so in-person spend still needs a bank card. It does not offer per-card spending limits, merchant locks, single-use numbers or a freeze button, and it has no team roles, so whoever signs in sees every card. Its security page also notes that payments requiring a 3-D Secure code cannot be completed with these cards, so another card is needed there. Each platform decides which cards it accepts, and ZenVCC may ask you to verify your identity before buying. You can read more about how ZenVCC handles account and card security, including what to do if card details leak.

    Key takeaways

    • Physical cards carry theft and skimming risk. Virtual cards remove that, but their numbers can still leak online.
    • The biggest security gain comes from giving each vendor or project its own number, which shrinks the blast radius of any leak.
    • Control features differ by provider, so confirm what a virtual card offers before you rely on it.
    • Count admin time, failed renewals and per-card fees, not only the card price.
    • Most small businesses do best with a physical card for in-person spend and virtual cards for recurring online charges.

    Start small: pick the three subscriptions that would hurt most if they failed, and move each one to its own card this month. If you want a prepaid option for that online spend, take a look at ZenVCC and compare its costs with your current setup.

  • Elegant Charters Introduces Corporate Transfers to Support Business Travel Across Perth

    Elegant Charters Introduces Corporate Transfers to Support Business Travel Across Perth

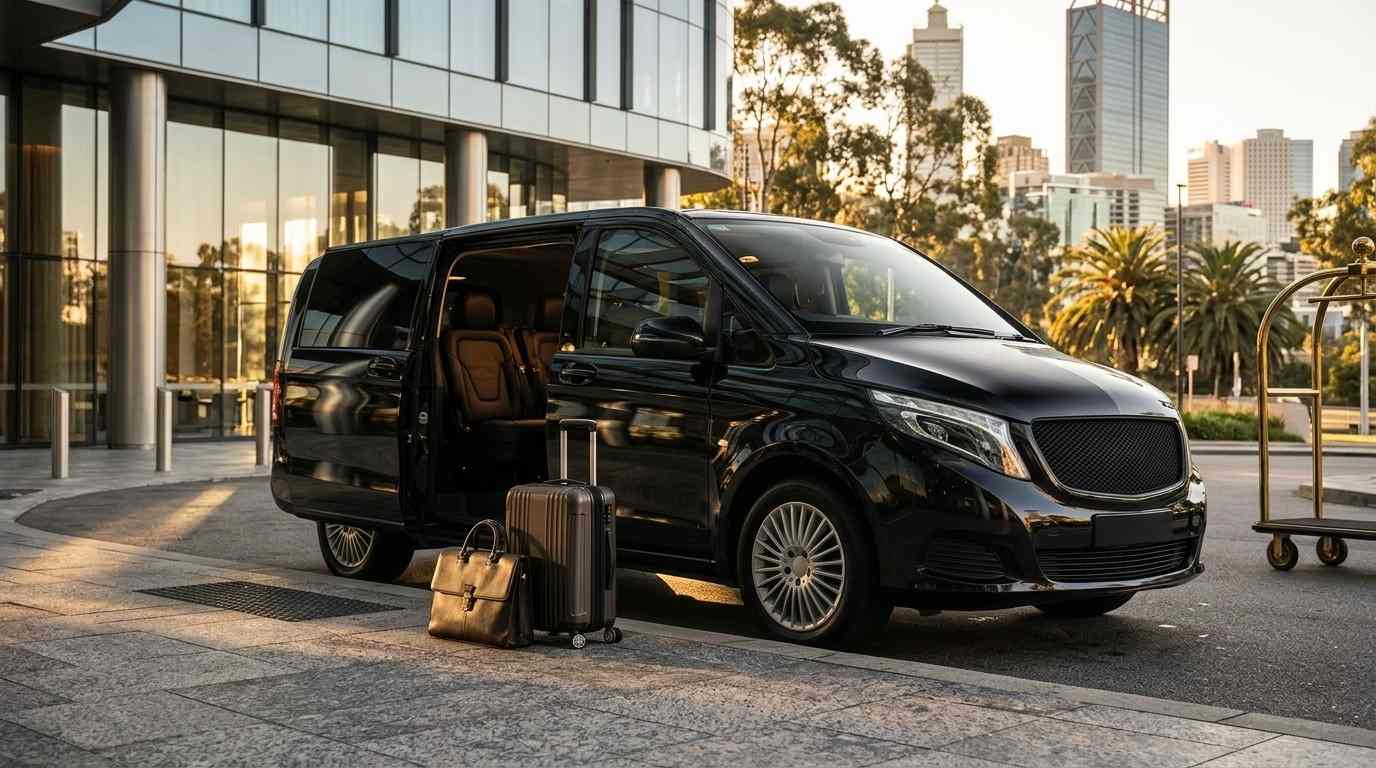
    Elegant Charters, a Perth-based chauffeur and passenger transportation provider, has introduced corporate transfer services designed to support the changing transportation needs of businesses, corporate professionals, and organisations across Perth and surrounding areas.

    The new service provides businesses with access to professional chauffeur-driven transportation for airport pickups, executive appointments, corporate meetings, conferences, business events, and other work-related journeys. The offering forms part of the company’s broader transportation services, which include airport transfers, private travel, group transportation, and long-distance journeys.

    Addressing the Changing Needs of Corporate Travel

    Reliable transportation remains an important consideration for businesses managing employee schedules, executive travel, client meetings, and professional events. Delays, inconsistent transport arrangements, and limited vehicle availability can create logistical challenges for organisations coordinating business travel.

    In Perth, businesses often require transportation solutions that accommodate different passenger numbers, travel schedules, and destination requirements. Corporate visitors arriving at Perth Airport may also need dependable transfers to hotels, offices, conference venues, and other business locations.

    These requirements have increased the importance of flexible ground transportation services that can accommodate both individual executives and larger corporate groups.

    Elegant Charters Responds With Dedicated Corporate Transfer Options

    Through its corporate transfer service, Elegant Charters aims to provide businesses with convenient access to professional chauffeur services and a range of passenger transportation options.

    The company offers a fleet comprising sedans, SUVs, vehicles accommodating four to seven passengers, and minibuses and maxi cabs with capacities ranging from 13 to 24 passengers. This range allows corporate clients to arrange transportation for individual travellers, small teams, and larger business groups.

    The service is designed to support different corporate travel requirements, including airport transportation, hotel transfers, business appointments, conferences, corporate functions, and scheduled journeys across Perth.

    Elegant Charters also provides 24-hour availability, online booking, flexible payment options, and personalised travel arrangements to assist customers with coordinating their transportation needs.

    Corporate Transfer Services and Transportation Options

    Elegant Charters provides several transportation options that can support corporate travel planning.

    These include:

    • Corporate Airport Transfers: Transportation between Perth Airport, business premises, hotels, and other destinations.
    • Executive Chauffeur Services: Private chauffeur-driven transportation for professionals, executives, and business visitors.
    • Corporate Event Transportation: Passenger transport for conferences, meetings, business functions, and corporate events.
    • Group Corporate Transfers: Minibus and maxi cab options for employee groups, visiting delegations, and business teams.
    • Hotel and Accommodation Transfers: Door-to-door transportation connecting corporate travellers with hotels and accommodation providers.
    • Long-Distance Business Travel: Private transportation for business-related journeys beyond central Perth.

    The company also offers additional transportation services, including FIFO transfers, cruise transfers, private tours, wedding transportation, and family travel arrangements.

    Supporting Business Travel Across Perth

    Based in Southern River, Western Australia, Elegant Charters serves customers requiring transportation throughout Perth and surrounding areas.

    Additional details are available at: https://share.google/FSAdcLsUiOwdP7pXf

    Its service model combines a range of vehicle capacities with online booking and flexible travel arrangements. Businesses can select transportation based on passenger numbers, journey requirements, and the nature of their corporate engagements.

    The company’s broader fleet options also provide flexibility for organisations that need to coordinate transportation for employees, visiting clients, conference attendees, and other business guests.

    By bringing corporate transportation together with its existing chauffeur and airport transfer services, Elegant Charters aims to simplify ground travel arrangements for businesses operating in and travelling to Perth.

    Company Background

    Elegant Charters provides chauffeur services and passenger transportation across Perth, Western Australia. Its services include airport transfers, corporate travel, private tours, weddings, events, hotel transfers, FIFO transportation, cruise transfers, and long-distance journeys.

    The company operates a fleet of sedans, SUVs, multi-passenger vehicles, minibuses, and maxi cabs designed to accommodate different travel requirements. Additional customer options include baby seats, personalised travel planning, flexible payment arrangements, and 24-hour online booking.

    Through its range of private and group transportation services, Elegant Charters supports individuals, families, business travellers, and organisations seeking professionally arranged ground transportation.

    Executive Statement

    A spokesperson for Elegant Charters said the introduction of corporate transfer services reflects the company’s focus on accommodating the transportation requirements of Perth’s business community.

    “Business travel often involves coordinating different schedules, destinations, and passenger requirements. Our corporate transfer service is designed to provide businesses with access to flexible vehicle options and professional chauffeur transportation for a range of work-related journeys,” the spokesperson said.

    Note: This is a proposed statement for company approval before publication.

    Looking Ahead

    As business travel and corporate transportation requirements continue to evolve, Elegant Charters plans to build on its existing chauffeur and passenger transport services to accommodate a wider range of customer needs.

    The introduction of corporate transfers represents an additional service offering for organisations seeking transportation for executives, employees, business visitors, and corporate groups.

    Businesses interested in arranging corporate transportation in Perth can learn more about the company’s services and booking options through its website.

    About Elegant Charters

    Elegant Charters is a Perth-based chauffeur and passenger transportation provider located in Southern River, Western Australia. The company offers airport transfers, corporate transfers, private chauffeur services, group transportation, tours, wedding transport, FIFO transfers, and long-distance travel.

    Its fleet includes sedans, SUVs, four- to seven-passenger vehicles, and 13- to 24-passenger minibuses and maxi cabs. Elegant Charters provides 24-hour availability, online booking, personalised travel arrangements, flexible payment options, and door-to-door transportation services.

    Media Contact

    Company: Elegant Charters – Airport Transfers Perth – Chauffeur Service Perth
    Location: Southern River, Western Australia, Australia
    Phone: +61 458 655 640
    Website: https://elegantcharters.com.au/

  • Valentine Services – Stump Grinding Announces Wood Chip Removal Service in Cincinnati, Ohio

    Valentine Services – Stump Grinding Announces Wood Chip Removal Service in Cincinnati, Ohio

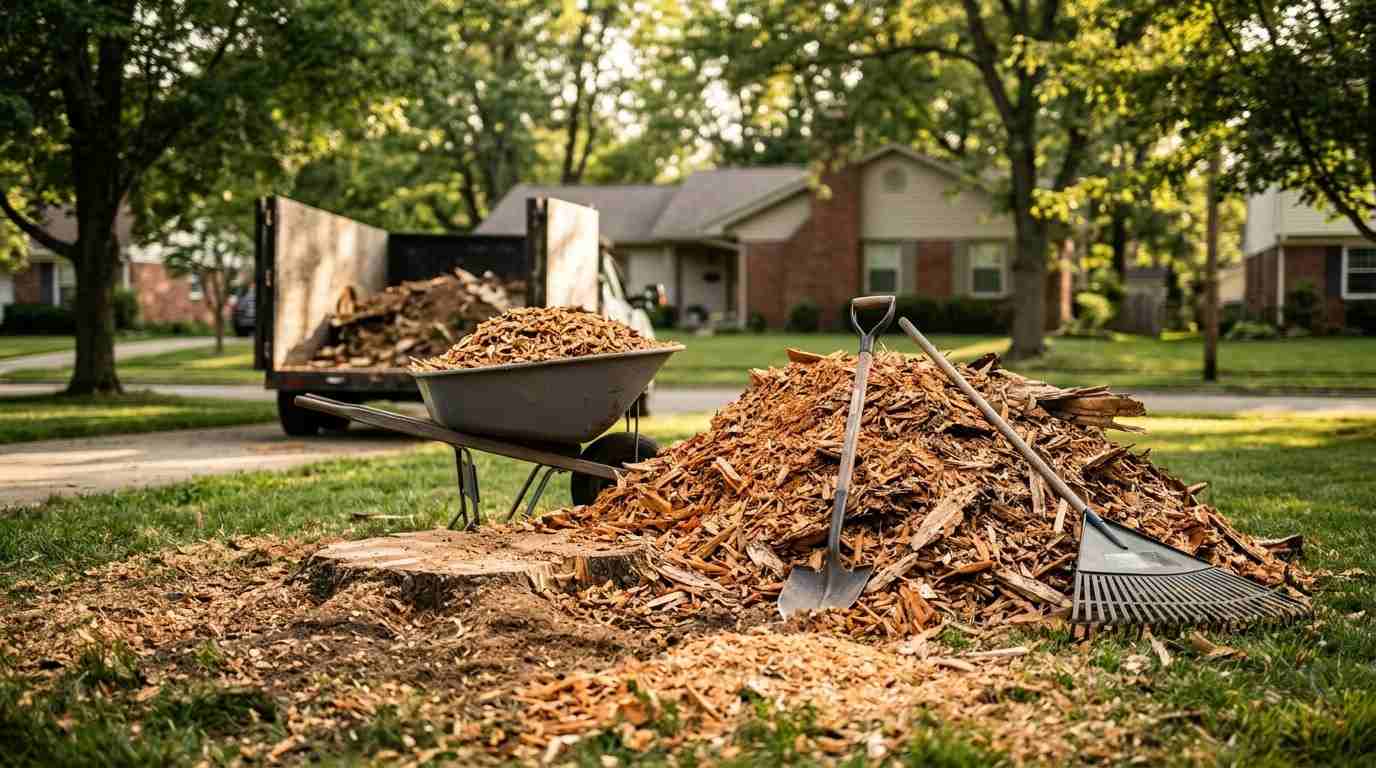
    Valentine Services – Stump Grinding has announced an expanded focus on wood chip removal services for residential and commercial properties throughout Cincinnati, Ohio, and surrounding communities. The service addresses the cleanup needs of property owners who are left with accumulated wood chips following tree removal, stump grinding, and other outdoor property maintenance projects.

    Addressing the Challenges of Wood Chip Cleanup

    Tree removal and stump grinding projects can leave behind substantial amounts of wood chips and other organic debris. While some property owners choose to reuse wood chips as landscaping material or mulch, others prefer to have the material removed to prepare their outdoor spaces for additional landscaping, lawn maintenance, or property improvements.

    Managing leftover wood chips can require additional time, equipment, and transportation. For homeowners, commercial property managers, contractors, and other property owners, arranging appropriate cleanup is an important part of completing outdoor projects.

    Valentine Services – Stump Grinding is addressing these needs by making wood chip removal an available part of its property cleanup solutions.

    Company Expands Property Cleanup Support

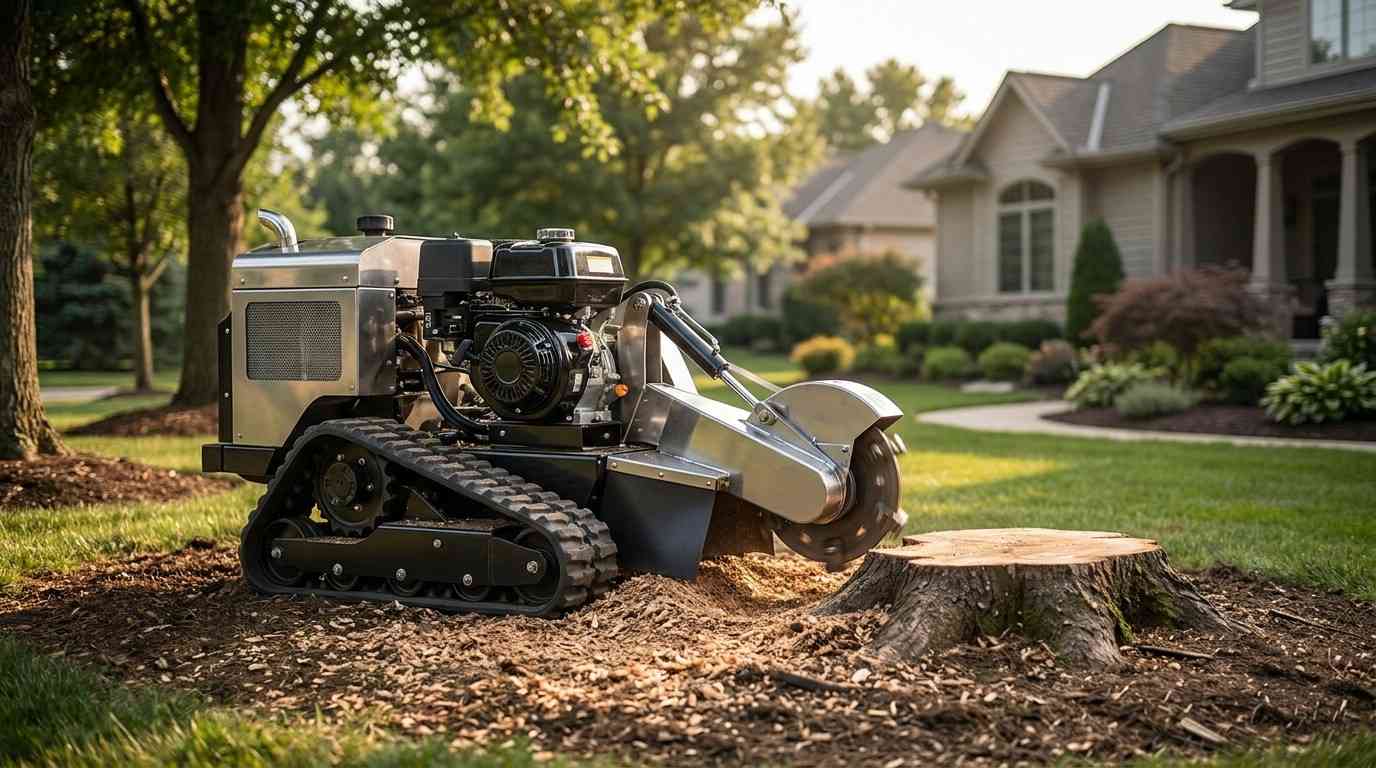
    Based in the Cincinnati area, Valentine Services – Stump Grinding provides stump grinding and removal services designed to help property owners reclaim usable outdoor space. Its services include stump grinding, surface root grinding, large stump removal, chip cleanup, and site restoration.

    Additional details are available at: https://share.google/FhICefWA6JHjY7oiz

    The company’s wood chip removal offering complements its existing stump grinding operations by providing property owners with an additional cleanup option after tree and stump-related work.

    By addressing leftover wood chips, the company aims to help customers prepare their properties for subsequent landscaping and outdoor maintenance activities.

    Wood Chip Removal and Related Services

    Valentine Services – Stump Grinding works with homeowners, businesses, property managers, and contractors throughout Greater Cincinnati and Northern Kentucky.

    Its service offerings include:

    • Wood Chip Removal: Removal of accumulated wood chips from outdoor work areas, subject to project requirements.
    • Residential Stump Grinding: Grinding unwanted tree stumps to help restore usable yard space.
    • Commercial Stump Grinding: Stump removal solutions for commercial properties and managed outdoor spaces.
    • Surface Root Grinding: Addressing exposed tree roots that may interfere with lawn maintenance and property use.
    • Large Stump Removal: Grinding solutions for larger tree stumps and challenging projects.
    • Chip Cleanup: Cleanup and haul-away options following stump grinding projects.
    • Site Restoration: Preparing affected areas for subsequent landscaping and lawn improvements.

    Service availability and project requirements can vary depending on the amount of material, site conditions, and access.

    Serving Cincinnati and Northern Kentucky Communities

    Valentine Services – Stump Grinding serves customers across Cincinnati and surrounding Ohio communities, including Blue Ash, Mason, West Chester, Fairfield, Loveland, and Hamilton.

    Its Northern Kentucky service area includes Florence, Covington, Erlanger, Burlington, Hebron, and nearby communities.

    The company works with residential and commercial customers seeking professional stump grinding, wood chip cleanup, and related property maintenance solutions.

    Company Background

    Valentine Services – Stump Grinding is a locally operated stump grinding and removal business serving Cincinnati, Ohio, and Northern Kentucky. The company provides services for homeowners, businesses, property managers, and contractors.

    Its work focuses on removing unwanted tree stumps, managing surface roots, addressing leftover wood chips, and helping restore outdoor spaces. The company reports that it is licensed and insured and provides free estimates for prospective projects.

    Looking Ahead

    As property owners continue to invest in landscaping, outdoor improvements, and routine property maintenance, cleanup remains an important consideration following tree-related projects.

    Valentine Services – Stump Grinding plans to continue supporting residential and commercial customers throughout Greater Cincinnati and Northern Kentucky with stump grinding, wood chip cleanup, and related services.

    Property owners interested in wood chip removal or stump grinding services can contact the company directly to discuss project requirements and request an estimate.

    About Valentine Services – Stump Grinding

    Valentine Services – Stump Grinding provides professional stump grinding and stump removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company serves residential and commercial customers with stump grinding, surface root removal, large stump grinding, wood chip cleanup, and site restoration. Valentine Services is licensed and insured and offers free estimates.

    Media Contact

    Valentine Services – Stump Grinding
    Email: bikemanjrv95@gmail.com
    Phone: 513-570-4626
    Website: https://www.513stumps.com/

  • Billing Thresholds 101: How Ad Platforms Charge You and How to Size Your Card Limits

    Billing Thresholds 101: How Ad Platforms Charge You and How to Size Your Card Limits

    You set a $100 daily budget, so you loaded $150 on the card. Then the platform charged $250 in one go, the card declined, and your ads stopped on the best day of the week.

    Quick answer

    1. On automatic billing, ad platforms charge your card when accrued spend reaches a billing threshold, or on a regular bill date, whichever comes first.

    2. A daily budget is an average, not a cap. Some days spend more.

    3. Size the card balance to the largest single charge you can get, not to the daily budget.

    4. Size the card’s monthly limit to the platform’s monthly maximum, plus headroom.

    What a billing threshold actually is

    A billing threshold is a running total. The platform delivers ads first and records the cost. When that total reaches a set amount, it sends an authorization to your card for the accrued amount and resets the counter.

    There is also a time trigger. If the threshold is not reached within the billing period, the platform charges whatever has accrued on the bill date. So a small account is charged on a schedule, and a busy account is charged every time it crosses the threshold, sometimes several times a day.

    How the three largest self-serve platforms describe it:

    PlatformWhen it chargesHow the threshold changesSource
    Google Ads (automatic payments)At the payment threshold, or on the first day of the monthCan rise automatically as costs reach it; you can edit it or opt out of automatic increasesGoogle Ads Help
    Meta Ads (automatic payments)At the billing threshold, or on the monthly bill dateStarts low on new accounts and rises with successful payments[VERIFY: Meta Business Help Center, “About billing thresholds”]
    TikTok Ads (automatic payment)At the billing threshold, or on the bill date (weekly or monthly)Not stated on TikTok’s help pageTikTok Ads Help

    Two consequences follow. The size of each charge is set by the threshold, not by your daily budget. The number of charges is set by how fast you spend relative to the threshold.

    Why your daily budget is not your daily charge

    Platforms treat the daily budget as an average they can move around to catch better traffic.

    • Google Ads says daily costs can reach up to twice your average daily budget, but you won’t be billed more than 30.4 times the daily budget in a month for most campaign types (Google Ads Help). The 30.4 is the average number of days in a month.
    • Meta describes a similar flexibility: on some days spend can run above the daily budget, while weekly spend stays within seven times the daily budget [VERIFY: Meta’s current daily overspend allowance, reported by third parties as up to 75%].
    • TikTok budgets can also deliver unevenly within a day [VERIFY: TikTok’s stated daily budget overspend rule].

    So a $100 daily budget on Google can produce a $200 day and about $3,040 in a month. A card sized for $100 a day will fail on the first hot day.

    Three formulas for sizing a card

    You need three numbers: your total daily budget across campaigns (D), your current billing threshold (T), and the platform’s peak-day multiplier (M, for example 2 on Google).

    1. Balance floor (what must always be on the card): Balance floor = T + (D × M) This covers a full threshold charge plus one peak day of spend that can accrue before your next top-up. Charges can come in slightly above the threshold, because spend keeps accruing while the charge is processed [VERIFY: whether each platform caps a threshold charge at exactly the threshold amount], so round up.

    2. Monthly limit (what the card must allow per month): Monthly limit ≥ D × 30.4 × 1.2 That is the monthly maximum with 20% headroom for budget increases you make mid-month.

    3. Funding cost (what a prepaid card costs you to load): Funding cost = monthly spend × top-up fee %

    Worked examples

    The thresholds below are illustrative. Use the one shown in your own billing settings.

    ScenarioD (daily)T (threshold)MBalance floorMonthly max (D × 30.4)Monthly limit with 20% headroom
    Small test$50$2502$350$1,520$1,824
    Steady campaign$150$5002$800$4,560$5,472
    Scaling account$400$7502$1,550$12,160$14,592

    Read the table from the right. The steady campaign’s monthly maximum of $4,560 almost fills a $5,000 monthly limit, and the 20% headroom pushes it over. That card would decline near the end of a strong month. The scaling account needs a limit above $14,500 or a lower budget.

    Now the funding cost. Loading $4,560 at a 2.5% top-up fee costs about $114 for the month. Put that in the media plan as a line item, not as a surprise.

    Where a prepaid card fits

    A prepaid card works well as a hard ceiling. It can never charge more than its balance, so a runaway campaign cannot overspend the money you set aside. The trade-off is that you must keep the balance above the floor, or threshold charges decline.

    As one worked example, VCCBuy’s Mastercard Prepaid has a $12.99 issue fee, a 2.5% top-up fee and a $10,000 monthly limit. It suits the “steady campaign” row above. The Visa Classic ($5,000 limit, 3% fee) fits the small test row. The Visa Premium ($25,000 limit, 2% fee) covers the scaling row. Balances are funded with stablecoins such as USDT or USDC and held in USD. Deposits are checked before they are credited, so top up a day before you need it, not at the moment a charge fails.

    Be honest about where this route stops. Google Ads does not accept prepaid cards for postpay (automatic) billing, according to Google Ads Help. A prepaid card only works there on a prepay setting, where available [VERIFY: whether Google Ads accepts prepaid cards for manual payments in the advertiser’s country]. Other platforms make their own checks too. VCCBuy is not a bank. A bank-issued virtual card or a business credit card with a set limit is the alternative for postpay billing.

    Procedure: setting thresholds and limits before launch

    1.  Find your threshold in each platform’s billing or payment settings. Write it down per ad account.

    2.  Add up D across every campaign in the ad account, including ones you plan to switch on this month.

    3.  Calculate the balance floor and the monthly limit with the formulas above.

    4.  Pick a card or tier whose monthly limit clears the monthly figure with headroom. Do not plan to “swap cards mid-month” as your safety margin.

    5.  Decide on the threshold. On Google you can set a lower threshold or opt out of automatic increases. A lower threshold means smaller, more frequent charges. A higher one means fewer, larger charges that each need a bigger balance. Pick the one your funding rhythm can cover.

    6.  Schedule top-ups so the balance never drops below the floor. A simple rule: each week, add at least D × 7 and check that the balance still sits above the floor afterward.

    7.  Turn on billing alerts in the platform and transaction notifications on the card.

    Pre-launch checklist

    ☐  Threshold recorded for every ad account

    ☐  Daily budget total includes all active and planned campaigns

    ☐  Card balance is above T + D × M

    ☐  Card monthly limit is above D × 30.4 × 1.2

    ☐  The card type is accepted for this platform’s billing setting

    ☐  Top-up fee is included in the media budget

    ☐  Top-ups scheduled ahead of expected charges, allowing for deposit checks

    ☐  Billing alerts and card notifications switched on

    FAQ

    Why was I charged before reaching my threshold? Because the bill date arrived first. Platforms charge whatever has accrued at the end of the billing period, even if it is below the threshold.

    Is it better to have a low or a high billing threshold? Neither is better in general. A low threshold keeps each charge small but creates more charges that can each fail. A high threshold means fewer charges, but each one needs a larger balance. Match the threshold to how often you can top up.

    Can my ad platform charge more than my daily budget in one day? Yes. Google says daily costs can reach twice the average daily budget for most campaigns, and other platforms allow some daily variation too. The monthly or weekly caps are what keep total spend in line.

    Conclusion

    Card declines on ad platforms are usually a math problem, not a card problem. Know your threshold, plan for peak days, and size the monthly limit to the platform’s monthly maximum. If you want a hard spending ceiling funded from stablecoins, compare a VCCBuy prepaid card with your bank’s virtual card options, and check that the platform’s billing setting accepts it.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about ad platform billing mechanics and how to size card balances so campaigns keep running.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • Ad Spend Reconciliation for Agencies: Matching Platform Invoices to Card Statements

    Ad Spend Reconciliation for Agencies: Matching Platform Invoices to Card Statements

    It is the third working day of the month. The client’s Meta dashboard says $18,420, the receipts add up to $18,105, and the card statement shows $18,960. Three numbers for one month of spend, and the client wants an invoice today.

    Quick answer

    1. The dashboard, the invoice and the card statement measure different things: delivery, billing and settlement.

    2. Most gaps come from five sources: timing, taxes, currency, credits, and failed or retried charges.

    3. Reconcile invoice to card first (they should match line by line), then invoice to dashboard (explain the difference).

    4. One card per client per platform, with a strict naming convention, makes both steps faster.

    Why three numbers never agree

    Each number comes from a different system, recorded at a different moment.

    • The dashboard shows delivery: the cost of impressions and clicks as they happen, in the ad account’s time zone. It can still change for days as invalid activity is filtered out.
    • The platform invoice or receipt shows billing: what the platform decided to charge, including tax and any credits.
    • The card statement shows settlement: what the card network actually moved, in the card’s currency, on the day it posted.

    Under threshold billing, the platform charges the card each time accrued spend reaches a set amount, plus once on a regular bill date. So spend delivered on 30 September can be charged on 2 October and land in October’s card statement. This is not an error. It is the normal gap between delivery and billing, and your process has to expect it.

    The five sources of variance

    VarianceWhat you seeWhere to find the evidenceHow to treat it
    TimingSpend from the last days of the month is charged in the next monthCharge date vs service period on each receiptAccrue it to the month it was delivered; note the carry-over
    TaxInvoice total is higher than dashboard spendVAT, GST or digital services tax lines on the invoiceSplit net spend from tax; tax may be recoverable depending on the client’s registration
    CurrencyCard amount differs from invoice amountAd account currency vs card currency; issuer FX rateRecord the card amount as the cost; note the rate used
    Credits and adjustmentsInvoice is lower than the dashboardCredit lines, invalid-activity adjustments, promo creditsPass credits through to the client; never absorb them silently
    Failed and retried chargesTwo attempts for one amount, or a charge missingCard transaction log (declines and approvals)Count only approved and posted charges; match each to one receipt

    A sixth, smaller item is your own funding cost. If a card is prepaid, the top-up fee is a real cost of the account. It does not appear on any platform invoice, so record it as a separate line.

    A naming convention that does half the work

    Reconciliation gets slow when you can’t tell which charge belongs to which client. Fix that at setup, not at month-end.

    Use one pattern everywhere: the card nickname, the ad account name, the folder for receipts and the line in your ledger.

    Pattern: CLIENT-PLATFORM-ACCOUNTID-PURPOSE

    • ACME-META-4471-PROSPECTING
    • ACME-GADS-9902-SEARCH
    • BLUEFIN-TIKTOK-1180-ALWAYSON

    Rules that keep it working:

    1.  One card per client per platform. A card shared by two clients turns every charge into a judgment call.

    2.  Use the platform’s own account ID in the name, so a receipt can be matched without opening the platform.

    3.  Never reuse a card name after a client leaves. Retire the card and the name together.

    4.  Keep receipts under the same name in a shared drive folder, by month: /ACME/2026-10/META/.

    Platform rules come first. The client’s ad account should be set up the way the platform expects for agency management, through Meta Business Manager, Google Ads manager accounts or TikTok Business Center, with the client’s business details where the platform requires them. A card per client is a bookkeeping tool. It does not change who owns an ad account or what the platform’s policies allow.

    Where a card-per-client setup fits

    Bank-issued virtual cards, corporate card programs and expense platforms all support card-per-client setups, and many agencies already have one. If your agency holds working funds in stablecoins, a crypto-funded prepaid card service is another option. VCCBuy’s cards-for-advertising page is one example. Each card can be renamed (so the naming pattern above becomes the card name), has its own transaction list, and can be frozen when a client pauses. You can save a billing name and address per card and withdraw unspent balance back to a crypto wallet. The Visa Premium tier has a 2% top-up fee and a $25,000 monthly limit, and the Mastercard Prepaid has a 2.5% fee and a $10,000 limit.

    The limits matter for reconciliation too. Prepaid cards are declined by some billing settings. Google Ads, for example, does not accept prepaid cards for postpay billing. Deposits are checked before they are credited, so plan top-ups ahead of threshold charges. VCCBuy is not a bank, and each ad platform runs its own checks on any card.

    The month-end close: a 7-step procedure

    Run it on the same working day each month, in this order.

    1.  Freeze the period. Note the last date in the month and the time zone of each ad account. A Pacific-time Google Ads account and a London card issuer disagree about where “midnight” falls.

    2.  Pull every receipt or invoice for each ad account into the client’s folder. Meta issues a receipt per charge, while Google Ads and TikTok can issue monthly invoices or statements depending on the billing setup [VERIFY: current invoice and receipt formats for each platform and billing mode in the client’s country].

    3.  Export the card transactions for each client card for the same period, including declined attempts.

    4.  Match invoice to card, line by line. Every approved card charge should match exactly one receipt by date and amount, allowing for FX. Flag any charge with no receipt, and any receipt with no charge.

    5.  Match invoice to dashboard. Take the dashboard’s spend for the period and explain the difference using the five-variance table: timing, tax, currency, credits, retries. Write the explanation down in one or two lines.

    6.  Add the funding cost. Record top-up fees or card fees for the period on a separate line, so client billing and agency cost stay distinct.

    7.  Sign off and lock. Save a one-page summary per client: dashboard spend, invoiced amount, card total, variance and the reason for it. Then lock the month in your ledger.

    A quick variance worksheet

    For the opening example, the worksheet might read:

    LineAmountNote
    Dashboard spend, 1–30 Sep$18,420Ad account time zone
    Less: invalid-activity credit−$315Shown on the last receipt
    Invoiced net spend$18,105Sum of receipts
    Add: tax on receipts$0Client is not charged tax in this market (illustrative)
    Less: charged in October for September delivery−$610Threshold hit on 2 Oct
    Add: August delivery charged in September$1,465Carry-over from last month
    Card statement, September$18,960Matches the card export

    These figures are illustrative. The point is the structure: every dollar between the three numbers has a named reason, and the client gets the same table every month.

    Pre-close checklist

    ☐  Every client card follows CLIENT-PLATFORM-ACCOUNTID-PURPOSE

    ☐  No card is shared between two clients or two platforms

    ☐  All receipts saved to the client’s month folder

    ☐  Card export includes declines, not only approvals

    ☐  Each approved charge is matched to exactly one receipt

    ☐  Carry-over from last month is recorded and cleared

    ☐  Credits are passed through to the client invoice

    ☐  Funding or top-up fees are on their own line

    ☐  Cards for paused or departed clients are frozen, and unused balances are dealt with

    FAQ

    Should I bill the client on dashboard spend or on invoiced spend? Bill on invoiced spend, which is what the platform actually charged after credits, and state the period clearly. Dashboard figures can change for days after delivery. Your contract should say which number you use.

    Why does the card show two charges of the same amount on one day? Usually one is a declined attempt followed by a successful retry, or the account hit its billing threshold twice. Check the card log for the approval status, and match only posted, approved charges to receipts.

    How do I handle currency differences between the ad account and the card? Treat the card amount as the actual cost and keep the platform invoice as the source document. To reduce the problem, open ad accounts in the currency the card settles in where the platform allows it.

    Conclusion

    Reconciliation is not about making three numbers equal. It is about naming every difference between them. Set up one card per client per platform, name everything the same way, and run the same seven steps on the same day each month. If you’re comparing card options for that setup, VCCBuy is one prepaid route to put next to your bank’s virtual cards and your expense platform.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They focus on how ad platforms bill cards and on keeping agency ad spend auditable from setup to month-end.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • SAP Cloud Platform Integration vs Traditional SAP Integration

    SAP Cloud Platform Integration vs Traditional SAP Integration

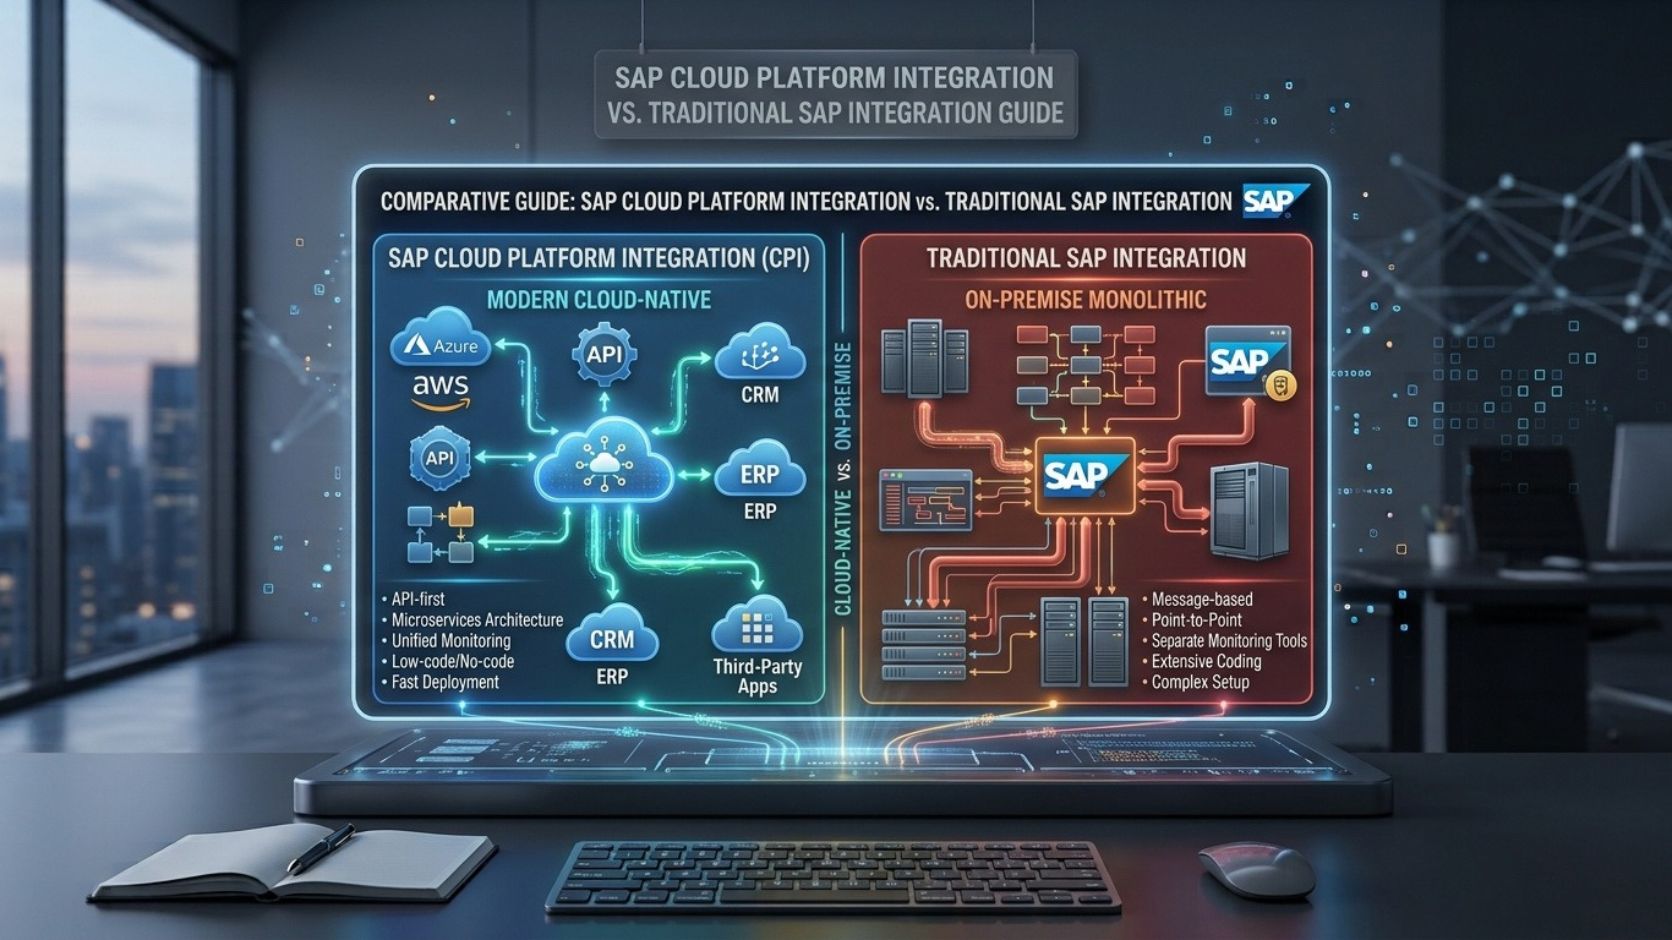
    SAP integration has changed as organizations have moved from on-premises systems toward cloud applications and hybrid IT environments. Traditional SAP integration commonly relies on technologies such as SAP Process Integration, SAP Process Orchestration, IDocs, RFC, and direct system connections. SAP Cloud Platform Integration provides a cloud-based approach for connecting SAP and non-SAP applications through integration flows, APIs, adapters, and managed connectivity.

    SAP Cloud Platform Integration is commonly known as SAP CPI. The capability is now part of SAP Integration Suite and is generally referred to as Cloud Integration. It supports cloud-to-cloud, cloud-to-on-premises, SAP-to-SAP, and SAP-to-non-SAP integration scenarios.

    Understanding the differences between SAP Cloud Platform Integration and traditional SAP integration requires comparing architecture, deployment, connectivity, development, security, monitoring, scalability, and connection management. Destinations can also play an important role in modern SAP cloud architectures.

    What Is SAP Cloud Platform Integration?

    SAP Cloud Platform Integration is a cloud-based integration service used to connect applications, APIs, SAP systems, and external platforms.

    It provides an integration layer where developers can create integration flows. These flows define how messages are received, transformed, routed, and delivered.

    A basic architecture is:

    Source System → Cloud Integration → Target System

    For example, SAP S/4HANA Cloud can exchange customer or order information with Salesforce through an integration flow.

    The flow can receive the message, validate the data, transform the structure, and send it to the target application.

    What Is Traditional SAP Integration?

    Traditional SAP integration refers to integration architectures based mainly on on-premises SAP systems and technologies.

    SAP Process Integration, or SAP PI, was widely used as an enterprise integration platform. SAP Process Orchestration, or SAP PO, extended integration and business process capabilities.

    Other traditional technologies include IDocs, RFC, BAPIs, SOAP services, and direct system connections.

    A traditional architecture may look like:

    SAP System → SAP PI/PO → External System

    The integration platform is generally deployed and managed within an organization’s infrastructure.

    This approach can support large and complex enterprise environments, particularly where core SAP systems remain on-premises.

    SAP Cloud Platform Integration vs Traditional SAP Integration

    The main difference is the deployment and architecture model.

    SAP Cloud Platform Integration operates as a cloud service. Traditional SAP integration platforms such as SAP PI and SAP PO are commonly associated with on-premises infrastructure.

    This difference affects infrastructure management, connectivity, deployment, scaling, maintenance, and integration with cloud applications.

    SAP Cloud Platform Integration is designed for modern hybrid and cloud integration requirements. Traditional SAP integration technologies remain relevant in environments that depend on existing on-premises systems and interfaces.

    Neither approach represents a single solution for every integration scenario. The appropriate architecture depends on the systems, interfaces, business requirements, security model, and deployment environment.

    Architecture Comparison

    Traditional SAP integration often uses an integration server deployed within the organization’s infrastructure.

    For example:

    SAP ERP → SAP PI/PO → External Application

    The organization is responsible for infrastructure, system administration, upgrades, networking, and other operational requirements associated with the platform.

    SAP Cloud Platform Integration uses a cloud-based integration runtime.

    A typical architecture is:

    SAP S/4HANA → Cloud Integration → Salesforce

    The cloud service provides the integration runtime and related platform capabilities.

    This architecture is designed to support applications distributed across cloud and on-premises environments.

    Deployment Differences

    Deployment is one of the clearest differences.

    Traditional SAP integration platforms are commonly installed within an organization’s data center or private infrastructure.

    This means the organization manages the underlying environment.

    SAP Cloud Platform Integration is delivered as a cloud service within SAP Integration Suite.

    Cloud deployment reduces the need for customers to install and maintain the integration runtime infrastructure themselves.

    The organization still needs to configure integration content, connectivity, authentication, monitoring, and other integration settings.

    Infrastructure Management

    Traditional SAP integration can require infrastructure planning for servers, operating systems, databases, networking, storage, backups, and system maintenance.

    SAP Cloud Platform Integration uses SAP-managed cloud infrastructure for the integration service.

    This changes the operational responsibilities of the organization.

    The customer focuses more on integration configuration, business logic, interfaces, security, monitoring, and connected systems instead of maintaining the underlying integration server infrastructure.

    Connectivity

    Traditional SAP integration often relies on technologies such as RFC, IDoc, SOAP, file transfer, and other SAP interfaces.

    Modern SAP cloud integration supports these types of enterprise scenarios while also providing connectivity for cloud applications and APIs.

    HTTP and REST-based integration are especially important in cloud architectures.

    For example:

    Cloud Application → REST API → Cloud Integration → SAP S/4HANA

    This model supports communication between applications that may operate in different cloud environments.

    APIs and Modern Integration

    APIs are an important part of modern application architecture.

    Traditional SAP systems can expose APIs through technologies such as SOAP, OData, RFC, and other interfaces.

    SAP Cloud Platform Integration can consume and process API requests from cloud applications and external platforms.

    REST APIs commonly use HTTP methods such as GET, POST, PUT, and DELETE. JSON is widely used for REST-based data exchange.

    This makes API-based integration a significant part of cloud integration architectures.

    The Role of Destinations

    Destinations are an important concept in SAP cloud environments.

    A Destination provides connection information that an application or service can use to communicate with another system.

    This information can include a target URL, authentication method, and other connection properties.

    In traditional integration architectures, connection information may be configured directly within integration systems or application configurations.

    Modern SAP cloud architectures can use Destinations to separate connection configuration from application logic where supported.

    For example, a development environment can use a test endpoint while production uses a live endpoint.

    Destinations can therefore help manage environment-specific connection information.

    The exact configuration depends on the SAP service, target system, and authentication method.

    Development and Integration Flow Design

    Traditional SAP PI/PO development commonly uses integration objects such as message types, interfaces, mappings, communication channels, and integration configurations.

    SAP Cloud Platform Integration uses graphical integration flows.

    An integration flow can contain a sender, receiver, adapters, mappings, routers, converters, content modifiers, scripts, and exception-handling components.

    For example:

    Sender → HTTP Adapter → Mapping → Router → Receiver

    This graphical model represents the message-processing sequence.

    The development approach is therefore aligned with cloud-based integration patterns while still supporting many enterprise integration requirements.

    Message Transformation

    Both traditional SAP integration and SAP Cloud Platform Integration support data transformation.

    Traditional SAP environments can use message mappings and transformation technologies associated with SAP PI/PO.

    SAP Cloud Platform Integration also provides message mapping and transformation capabilities.

    For example, a source application may provide:

    Customer_ID

    while the target application requires:

    CustomerNumber

    The integration layer maps the source field to the target field.

    Transformation can also include data type conversion, value changes, field combinations, and structural changes.

    Monitoring and Error Handling

    Both traditional and cloud integration platforms provide monitoring capabilities.

    Traditional SAP PI/PO environments can use platform-specific monitoring tools to track message processing.

    SAP Cloud Platform Integration provides cloud-based monitoring for integration artifacts and message processing.

    Administrators can investigate errors such as invalid data, failed authentication, unavailable endpoints, mapping problems, and target-system failures.

    Exception handling can be configured inside integration flows.

    This allows technical teams to separate successful processing from failed processing and investigate problems more efficiently.

    Security Comparison

    Security requirements exist in both traditional and cloud integration environments.

    Traditional SAP integration can use enterprise network controls, certificates, authentication mechanisms, firewall rules, and other security technologies.

    SAP Cloud Platform Integration supports authentication mechanisms such as OAuth, basic authentication, client certificates, and other supported methods.

    HTTPS can encrypt data during transmission.

    Cloud environments also require careful management of identities, credentials, permissions, endpoints, and certificates.

    The specific security architecture depends on the connected applications and organizational requirements.

    The Role of Destinations in Modern SAP Integration

    Destinations can simplify how cloud applications access external services.

    For example, a cloud application may need to access an SAP API. Instead of embedding the endpoint and authentication information directly into application code, the application can use a configured Destination where supported.

    This can help separate technical connection settings from business logic.

    Traditional SAP integration can use different connection mechanisms based on the technology and architecture.

    The use of Destinations is therefore more closely associated with SAP’s cloud application and connectivity architecture.

    Cloud-to-Cloud Integration

    Traditional SAP integration was primarily designed around enterprise systems that often operated within controlled network environments.

    Modern businesses commonly use several cloud applications.

    For example:

    SAP S/4HANA Cloud

    SAP SuccessFactors

    Salesforce

    External Logistics Platform

    These systems may operate in different cloud environments.

    SAP Cloud Platform Integration can provide a central integration layer between them.

    The integration flow can receive data from one cloud application, transform it, and send it to another application through APIs or supported adapters.

    Hybrid Integration

    Many organizations still operate a combination of cloud and on-premises systems.

    For example, SAP ERP may remain on-premises while CRM and HR applications operate in the cloud.

    A hybrid architecture can connect these environments through SAP Cloud Platform Integration and appropriate secure connectivity.

    A typical architecture can be:

    On-Premises SAP System → Secure Connectivity → Cloud Integration → Cloud Application

    This allows organizations to connect existing SAP infrastructure with newer cloud applications.

    Scalability and Operations

    Traditional integration platforms require infrastructure planning based on expected message volume, system capacity, and processing requirements.

    Cloud integration changes the infrastructure management model because the integration service operates within SAP’s cloud environment.

    However, integration performance still depends on message size, message volume, processing complexity, network conditions, and the capacity of connected systems.

    Architecture planning is still necessary for high-volume integrations.

    The use of Destinations can also support connection configuration across cloud application environments where appropriate.

    Maintenance and Upgrades

    Traditional SAP PI/PO environments require customers to manage system maintenance, patches, upgrades, operating system dependencies, and infrastructure components according to their deployment model.

    With SAP Cloud Platform Integration, SAP manages the underlying cloud service infrastructure.

    Customers still need to maintain integration flows, mappings, credentials, endpoints, certificates, and connected-system configurations.

    This creates a different operational model rather than eliminating integration management.

    When to Use SAP Cloud Platform Integration

    SAP Cloud Platform Integration is suitable for scenarios involving cloud applications, APIs, hybrid environments, and SAP-to-non-SAP connectivity.

    It is particularly relevant when an organization needs to connect applications distributed across cloud and on-premises environments.

    Examples include S/4HANA integration, SuccessFactors integration, Salesforce connectivity, API integration, e-commerce integration, and third-party logistics systems.

    When Traditional SAP Integration Is Still Relevant

    Traditional SAP integration remains relevant where existing SAP PI/PO environments support established business processes.

    Organizations may have hundreds of existing interfaces based on IDocs, RFC, SOAP, or other technologies.

    Migrating these interfaces requires planning, testing, security analysis, and business validation.

    An organization may therefore operate traditional and cloud integration technologies together during a transition period.

    The appropriate approach depends on the current architecture and future integration requirements.

    Migration from Traditional SAP Integration to Cloud Integration

    Moving from SAP PI/PO to SAP Cloud Platform Integration requires an integration assessment.

    Existing interfaces should be reviewed to determine their protocols, mappings, dependencies, authentication methods, message volumes, and business importance.

    The migration process may involve redesigning some integrations rather than simply copying them.

    For example, an existing SOAP integration may be redesigned around an API-based architecture when the target application provides an appropriate API.

    Testing is required to verify that migrated interfaces produce the expected results.

    Production migration should be planned to avoid disruption to critical business processes.

    Frequently Asked Questions

    What is the difference between SAP CPI and traditional SAP integration?

    SAP Cloud Platform Integration is a cloud-based integration service, while traditional SAP integration commonly uses on-premises technologies such as SAP PI, SAP PO, RFC, IDoc, and SOAP-based interfaces.

    Is SAP Cloud Platform Integration the same as SAP CPI?

    Yes. SAP CPI is the commonly used abbreviation for SAP Cloud Platform Integration. The capability is now part of SAP Integration Suite and is generally called Cloud Integration.

    Are Destinations used in SAP Cloud Platform Integration?

    Destinations are used in SAP cloud environments to provide connection information for applications and services. Their exact role depends on the application architecture and integration scenario.

    What are Destinations used for?

    Destinations can contain information such as a target URL, authentication method, and connection properties. They can separate connection configuration from application logic where supported.

    Is SAP PI still used?

    Existing SAP PI environments continue to operate in many organizations. However, SAP’s integration portfolio has evolved toward SAP Integration Suite and cloud-based integration capabilities.

    Can SAP Cloud Platform Integration connect on-premises systems?

    Yes. It can participate in hybrid architectures that connect on-premises SAP systems with cloud applications through appropriate connectivity mechanisms.

    Which is better for cloud integration?

    The appropriate technology depends on the architecture. Cloud-based integration is designed for cloud and hybrid scenarios, while existing traditional integration platforms may continue to support established on-premises interfaces.

    Can SAP Cloud Platform Integration use APIs?

    Yes. API-based integration is an important part of modern cloud integration. REST, SOAP, OData, and other supported technologies can be used depending on the integration scenario.

    Conclusion

    SAP Cloud Platform Integration and traditional SAP integration use different architectural approaches to solve enterprise connectivity requirements.

    Traditional SAP integration commonly relies on on-premises technologies such as SAP PI, SAP PO, RFC, IDocs, and SOAP. SAP Cloud Platform Integration provides a cloud-based integration environment designed for modern cloud, hybrid, API-based, SAP-to-SAP, and SAP-to-non-SAP scenarios.

    The main differences involve deployment, infrastructure management, connectivity, development models, cloud application support, monitoring, and operational responsibilities.

    Destinations are another important part of modern SAP cloud architecture. They can provide reusable connection information and help separate endpoint configuration from application logic in supported scenarios.

    For organizations with existing SAP PI or SAP PO environments, migration does not necessarily mean replacing every interface immediately. Existing interfaces should be assessed individually based on technology, business requirements, security, dependencies, and future architecture.

    As SAP environments continue to combine cloud and on-premises applications, SAP Cloud Platform Integration provides a cloud-based approach for managing integration across these systems.
  • Same-Day Stump Grinding for Cincinnati Homes and Businesses

    Same-Day Stump Grinding for Cincinnati Homes and Businesses

    Valentine Services – Stump Grinding has introduced a new same-day stump grinding service for homeowners, businesses, property managers and contractors in Cincinnati, Ohio, and surrounding communities.

    The new service is designed for property owners who need unwanted tree stumps addressed without an extended scheduling process. Same-Day Stump Grinding expands Valentine Services’ existing range of stump and root grinding solutions while providing another scheduling option for customers dealing with tripping hazards, obstructed outdoor areas or stumps left after tree removal.

    Addressing Common Property Maintenance Challenges

    Tree stumps can remain on a property after a tree has been removed, creating obstacles for landscaping projects, lawn maintenance and property improvements. Surface roots can also interfere with walkways, planting areas and other uses of outdoor space.

    Additional details are available at: https://share.google/FhICefWA6JHjY7oiz

    For residential and commercial property owners, addressing these remnants can be part of preparing a property for landscaping, construction or routine maintenance. A grinding approach can reduce the visible portion of a stump and leave wood chips that can be incorporated into the property’s restoration plan.

    Valentine Services Adds Same-Day Scheduling

    Valentine Services – Stump Grinding is responding to these needs with its new Same-Day Stump Grinding service. The company serves customers throughout Cincinnati and Northern Kentucky, with service availability extending to communities including Blue Ash, Mason, West Chester, Fairfield, Loveland, Hamilton, Florence, Covington, Erlanger and Burlington.

    Same-day requests are subject to scheduling and site conditions. Customers can contact the company to discuss their stump grinding needs and request an estimate.

    Stump Grinding and Property Restoration Services

    Valentine Services provides several stump-related services for residential and commercial properties, including:

    The company works with homeowners as well as businesses, property managers and contractors. Its services are intended to address unwanted stumps, surface roots and related tripping hazards while supporting subsequent landscaping or property maintenance work.

    Company Background

    Valentine Services – Stump Grinding provides stump grinding and stump removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company focuses on removing unwanted tree stumps and surface roots from residential and commercial properties.

    The company serves Cincinnati and nearby communities and states that it is licensed and insured. Valentine Services also provides free estimates as part of its customer service process.

    Executive Statement

    “Adding same-day stump grinding gives property owners another option when they need to address an unwanted stump promptly,” said a representative of Valentine Services – Stump Grinding. “We continue to focus on dependable service, clear communication and practical solutions for residential and commercial properties throughout the Cincinnati and Northern Kentucky area.”

    Future Outlook

    The introduction of Same-Day Stump Grinding reflects Valentine Services’ continued focus on providing flexible stump removal and grinding options for the communities it serves. The company plans to continue supporting homeowners, businesses, property managers and contractors with stump grinding, root grinding, cleanup and site restoration services.

    Customers in Cincinnati and surrounding communities can contact Valentine Services – Stump Grinding to discuss service needs and request a free estimate.

    About Valentine Services – Stump Grinding

    Valentine Services – Stump Grinding provides professional stump grinding and stump removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company specializes in removing unwanted tree stumps, surface roots and tripping hazards for homeowners, businesses, property managers and contractors. Services include residential and commercial stump grinding, root grinding, large stump removal, chip cleanup and site restoration. Valentine Services serves Cincinnati, Blue Ash, Mason, West Chester, Fairfield, Loveland, Hamilton, Florence, Covington, Erlanger, Burlington, Hebron and nearby communities. The company is licensed and insured and provides free estimates.

    Media Contact

    Valentine Services – Stump Grinding
    Email: bikemanjrv95@gmail.com
    Phone: 513-570-4626
    Website: https://www.513stumps.com/

  • New Shoulder Pain Treatment Service Launches in Sydney

    New Shoulder Pain Treatment Service Launches in Sydney

    Spine and Posture Care Chiropractor Sydney has introduced a new shoulder pain treatment service as the Sydney chiropractic clinic expands its focus on musculoskeletal care and individualized treatment programs.

    The new service is designed for people experiencing shoulder pain and related movement or posture concerns. The clinic’s chiropractors assess each patient to identify potential contributing factors before developing an individualized care plan based on the patient’s presentation and goals.

    Addressing a Common Musculoskeletal Challenge

    Shoulder pain can affect everyday activities, including reaching, lifting, working at a desk and maintaining comfortable posture. Its causes can vary, making assessment an important part of determining an appropriate approach to care.

    Additional details are available at: https://share.google/O8QKN1qUIOwGNrFeU

    Spine and Posture Care’s broader clinical approach focuses on identifying the source of a patient’s pain or posture-related concern rather than applying a uniform treatment program. The clinic provides chiropractic care for conditions and concerns involving the lower back, mid-back and neck, as well as sciatica, headaches, slipped discs and poor posture.

    Clinic Response

    With the addition of shoulder pain treatment, Spine and Posture Care is extending its existing musculoskeletal care services to address another area commonly associated with pain and restricted movement.

    Patients receive one-on-one care and explanations of their treatment plan. Depending on individual needs, the clinic combines spinal therapy, muscle work and rehabilitation within tailored chiropractic programs.

    The approach is intended to provide patients with a clearer understanding of their condition and the role of each component of their treatment plan.

    Shoulder Pain Treatment Service

    The new shoulder pain service incorporates assessment and individualized chiropractic care. Treatment plans may involve a combination of manual techniques, muscle work and rehabilitation based on the findings of the clinical assessment.

    The clinic emphasizes evidence-based treatment planning and patient education, with care programs developed around individual circumstances rather than a standardized protocol.

    About Spine and Posture Care

    Spine and Posture Care Chiropractor Sydney is a chiropractic clinic located in Sydney, NSW, between Wynyard, Martin Place and Circular Quay.

    The clinic focuses on identifying contributing factors behind pain and posture-related concerns and developing tailored treatment programs. Its chiropractors provide one-on-one care for lower back, mid-back and neck pain, sciatica, headaches, slipped discs, poor posture and other musculoskeletal concerns.

    The clinic combines spinal therapy, muscle work and rehabilitation as part of individualized chiropractic treatment plans. Spine and Posture Care has also established a substantial body of patient reviews and serves people in and around Sydney City.

    Executive Statement

    A clinic representative said the addition of shoulder pain treatment reflects the practice’s broader approach to individualized musculoskeletal care.

    “Shoulder pain can have different contributing factors, so our focus is on understanding the individual presentation and explaining the available treatment approach clearly,” the representative said. “The new service allows us to extend our existing focus on personalized chiropractic care to patients seeking help with shoulder-related concerns.”

    Future Outlook

    Spine and Posture Care plans to continue developing its chiropractic services around individualized assessment, patient education and rehabilitation. The clinic’s broader objective is to help patients understand the factors contributing to their pain or posture concerns while providing structured treatment programs suited to their needs.

    The new shoulder pain treatment service is now available through the clinic in Sydney, NSW.

    About the Company

    Spine and Posture Care Chiropractor Sydney is a Sydney-based chiropractic clinic providing individualized care for pain and posture-related concerns. The clinic’s services include chiropractic treatment for lower back, mid-back and neck pain, sciatica, headaches, slipped discs, poor posture and shoulder pain.

    The practice provides one-on-one consultations, patient education, spinal therapy, muscle work and rehabilitation as part of tailored treatment plans. It is conveniently located in Sydney City between Wynyard, Martin Place and Circular Quay.

    Media Contact

    Spine and Posture Care Chiropractor Sydney
    Email: Info@spineandposturecare.com.au
    Phone: +61 2 8040 9922
    Website: https://spineandposturecare.com.au/

  • The Future of Card Issuing: AI-Driven Spend Controls and Dynamic Limits

    The Future of Card Issuing: AI-Driven Spend Controls and Dynamic Limits

    Card issuing is shifting from static rules to adaptive controls shaped by AI and real-time data. Fixed limits often fail when spending patterns change, creating friction for employees and blind spots for risk teams. Dynamic limits promise faster decisions, tighter oversight, and more precise access to funds. Yet their value depends on the quality of data, governance, and issuer infrastructure. The critical question is not whether this model will expand, but how far it can be trusted.

    What Is AI-Driven Card Issuing?

    How does AI-driven card issuing differ from conventional payment provisioning? It uses machine learning and real-time data to configure payment credentials, limits, and authorization parameters according to context, rather than relying on fixed, manually defined settings.

    This model improves card flexibility by adapting issuance rules to transaction patterns, business policies, and user roles. Among the primary AI benefits are faster decisioning, more relevant controls, and stronger risk management through continuous anomaly detection.

    AI-driven issuing also supports spend optimization by aligning card behavior with operational objectives and approved purchasing categories.

    For administrators, it produces deeper financial insights from aggregated transaction signals and behavioral trends.

    For end users, the resulting user experience is more seamless, because appropriate permissions, funding access, and payment functionality can be provisioned with greater accuracy and speed.

    Why Static Spend Controls Fail

    Although static spend controls are designed to enforce consistency, they often fail in environments where purchasing behavior, vendor risk, and operational needs change too quickly for fixed rules to remain effective. Their static limitations prevent timely responses to market shifts, supplier changes, and urgent exceptions.

    As a result, outdated strategies can block legitimate transactions while overlooking emerging threats, increasing user dissatisfaction and risk exposure.

    Rigid thresholds also create compliance challenges when regulatory expectations evolve faster than policy updates. Teams may resort to manual overrides, introducing operational inefficiencies and weakening audit reliability.

    Across distributed organizations, fixed controls can produce spending inconsistencies between departments with different purchasing patterns, priorities, and approval needs. They are particularly ineffective under budget constraints, where tighter oversight must still accommodate necessary flexibility and uninterrupted business continuity requirements.

    How Dynamic Card Limits Work

    Dynamic card limits address these shortcomings by replacing fixed spending thresholds with controls that adjust in response to context, risk, and policy conditions. Instead of assigning a permanent cap, the issuer evaluates transaction variables such as merchant category, amount, location, timing, user history, and available budget.

    Rules engines and machine learning models then recalculate permissible spend in real time. This approach allows dynamic limits to tighten when anomalies appear and expand when transactions align with approved patterns.

    Controls can also reflect policy hierarchies, project budgets, cash flow status, or fraud signals without manual intervention. The result is greater precision in authorization decisions, reduced false declines, and stronger governance.

    Where Dynamic Controls Help Employees

    Several employee spending scenarios benefit most from adaptive controls, particularly when purchase needs vary across roles, locations, and timing. Field staff, sales teams, project managers, and traveling executives often face variable costs that static card rules handle poorly.

    Dynamic controls improve employee empowerment by aligning available funds with legitimate business context, reducing delays, exceptions, and manual approvals. They also support adaptive budgeting, allowing organizations to respond to changing operational demands without abandoning policy discipline.

    In practice, personalized controls can expand merchant access, adjust limits for travel days, or permit urgent procurement within defined parameters. This creates financial flexibility while preserving spending transparency across decentralized purchasing activity.

    Employees gain smoother access to necessary resources, and finance teams retain expense accountability through governed, real time authorization boundaries and clearer policy enforcement.

    What Data Powers AI Spend Controls

    Data is the operational foundation of AI-driven spend controls, enabling authorization logic to reflect real business conditions rather than static policy thresholds.

    Effective models draw from multiple data sources, including transaction history, merchant category detail, time, location, and approved budget parameters. They also evaluate spending patterns across teams, vendors, and periods to distinguish ordinary operational variance from policy exceptions.

    Signals derived from user behavior, such as booking timing, device consistency, and approval routing, add organizational context. Predictive analytics then convert these inputs into forward-looking recommendations for limits, merchant restrictions, and escalation rules.

    To remain reliable, models must be calibrated against financial metrics, internal policy rules, and external compliance standards. This structured data framework improves risk assessment while supporting adaptive, context-aware spending governance across distributed organizations and geographies.

    How AI Reduces Fraud and False Declines

    The same data architecture that supports adaptive spend controls also improves the accuracy of fraud prevention by separating suspicious activity from legitimate exceptions.

    By analyzing merchant patterns, transaction velocity, device signals, geography, and historical behavior simultaneously, AI refines fraud detection beyond static rules.

    This approach strengthens risk assessment at authorization, where models estimate whether unusual activity reflects compromise or a valid change in spending context. As a result, issuers can block high-risk transactions earlier while approving atypical but explainable purchases more consistently.

    False declines fall because decisions rely on probabilistic patterns rather than isolated triggers such as amount thresholds or foreign locations alone.

    Over time, feedback loops from confirmed fraud, cardholder verification, and dispute outcomes improve model precision, reducing operational losses while preserving cardholder trust and payment continuity across channels and markets worldwide.

    Paying International Suppliers From Local Markets

    Multi-currency virtual cards let users hold value in one currency and spend across borders without maintaining foreign accounts. The mechanics — funding currency, settlement currency, and FX handling — matter enormously for cost. Markets with heavy cross-border demand illustrate this best: the adoption of the virtual card API for Nigerian businesses is driven largely by companies paying international suppliers and subscriptions in dollars.

    How Issuers Set AI Guardrails

    Issuers set AI guardrails by translating risk appetite into real-time risk thresholds that govern transaction approvals, declines, and step-up actions.

    These thresholds are typically paired with policy-based limit models that define acceptable spending conditions by customer segment, merchant category, geography, and time.

    Together, these controls frame how automated decisions remain both adaptive and bounded within institutional rules.

    Real-Time Risk Thresholds

    Because fraud patterns can shift within minutes, real-time risk thresholds function as the operational guardrails that constrain AI-driven authorization decisions. Issuers calibrate these thresholds through continuous risk assessment, combining transaction monitoring with behavioral analytics to identify anomalies against established spending patterns.

    The objective is not static denial rules, but rapid fraud detection with measurable tolerance bands for velocity, merchant type, geography, and device signals.

    Threshold design must also reflect compliance requirements, including explainability, auditability, and fair treatment across customer segments. Models are therefore evaluated against false-positive rates, approval lift, and escalation accuracy.

    User feedback, chargeback outcomes, and investigator reviews supply corrective signals that support disciplined threshold adjustments. In practice, effective guardrails balance responsiveness and stability, allowing interventions to tighten quickly without creating unnecessary friction or materially degrading legitimate transaction flow.

    Policy-Based Limit Models

    Most policy-based limit models translate broad risk appetite into explicit spending constraints that AI systems can enforce at authorization time. Issuers define merchant-category caps, geographic restrictions, velocity rules, and role-based thresholds, then encode them into decision engines that evaluate each transaction against approved parameters.

    These models matter because adaptive limits without governance can drift toward inconsistency or hidden bias. A policy layer creates traceable logic for policy enforcement, ensuring dynamic adjustments remain bounded by predetermined tolerances.

    AI may recommend temporary expansions or tighter controls, but only within approved bands linked to customer segment, fraud exposure, and regulatory obligations. This structure also supports compliance monitoring by preserving auditable rationales, exception histories, and override records.

    As a result, issuers gain flexibility while maintaining accountability, repeatability, and defensible control over spend authorization outcomes.

    What Real-Time Card Issuing Requires

    Real-time card issuing depends on instant authorization infrastructure that can provision, validate, and approve transactions with minimal latency.

    It also requires real-time risk decisioning to assess context, detect anomalies, and enforce policy at the moment of spend.

    Supporting both functions, adaptive control frameworks enable issuers to adjust limits, rules, and permissions continuously as conditions change.

    Instant Authorization Infrastructure

    Instant authorization infrastructure depends on a tightly integrated stack that can issue, evaluate, and approve or decline card transactions within milliseconds. It requires resilient issuer processing, low-latency network connectivity, tokenization support, ledger synchronization, and highly available APIs linking card programs to banking cores.

    Effective instant approval systems rely on deterministic routing, standardized message formats, and rapid data propagation across processors, wallets, and merchant acquirers.

    Operational performance depends on transaction speed enhancements such as edge-based processing, optimized database reads, in-memory state management, and automated failover. The infrastructure must also support real-time balance visibility, dynamic card status updates, and configurable authorization rules without interrupting service continuity.

    Strong observability, redundant architecture, and precise timestamping are essential for maintaining consistency, reducing false declines, and supporting scalable issuing programs across geographies and payment rails globally.

    Real-Time Risk Decisioning

    Effective real-time risk decisioning requires each card authorization to be assessed against contextual signals, policy rules, and behavioral models within the narrow time constraints of network approval windows. This demands high-speed risk assessment that combines transaction analysis with current merchant, device, geolocation, and velocity data.

    Systems must support fraud detection and compliance monitoring simultaneously, without degrading approval performance. Behavioral insights derived from spending patterns, user feedback, and historical account activity improve precision by distinguishing anomalous behavior from legitimate exceptions.

    Machine learning and predictive analytics strengthen decision quality by identifying subtle correlations that static thresholds often miss. Automated alerts then surface elevated-risk events for review, while preserving straight-through processing for ordinary transactions.

    The result is a decision layer that balances security, accuracy, operational efficiency, and customer continuity at scale.

    Adaptive Control Frameworks

    Because authorization conditions can change from one transaction to the next, adaptive control frameworks are required to translate policy intent into dynamic, low-latency decisions at the point of issuance. They combine rule engines, event streams, and model outputs to enforce adaptive spending policies without interrupting user experience.

    Effective frameworks also support flexible limits, adjusting thresholds by merchant type, time, geography, budget state, and risk posture.

    • Contextual signals refine each authorization decision.
    • Policy hierarchies preserve governance and auditability.
    • Real-time feedback loops improve model calibration.
    • Exception handling reduces false declines and friction.
    • API orchestration connects issuing, ledger, and controls.

    Such architectures enable issuers to respond proportionally rather than uniformly. In practice, this means greater precision, stronger compliance alignment, and more resilient spend control under changing transaction conditions and evolving business constraints.

    How to Measure Card Program Results

    A disciplined measurement framework is essential for determining whether an AI-driven card program improves control, efficiency, and policy adherence. Effective performance evaluation begins with selecting card program metrics that connect operational outputs to financial and compliance outcomes.

    Core indicators include authorization approval accuracy, exception rates, fraud losses, false declines, average intervention time, policy violation frequency, and working capital impact.

    Measurement should compare baseline performance against post-deployment results across cardholder segments, merchant categories, and risk tiers. It should also assess model responsiveness by tracking how quickly limits and controls adapt to behavioral changes without increasing employee friction.

    Qualitative inputs, including finance, procurement, and employee feedback, help contextualize numerical trends. A reliable review cadence, supported by clean data governance, enables continuous calibration and defensible assessment of program value over time.

    What’s Next for Adaptive Card Controls?

    How will adaptive card controls evolve as AI capabilities, payment data richness, and enterprise risk expectations continue to advance? The next phase will likely center on continuous decisioning, where models refine limits and rules in real time using merchant signals, context, and user behavior.

    Rather than static policies, issuers may deploy adaptive spending frameworks that align controls with intent, risk, and operational urgency.

    • Real-time limit calibration by transaction context
    • Behavioral baselines updated from user behavior patterns
    • Policy orchestration across departments and geographies
    • Explainable AI outputs for audit and compliance review
    • Tighter fraud, treasury, and procurement integration layers

    As these systems mature, competitive differentiation will depend on transparency, governance, and measurable accuracy, not automation alone.

    Enterprises will expect controllable intelligence that balances flexibility, accountability, and resilience.

    Frequently Asked Questions

    How Long Does AI Card Issuing Implementation Typically Take?

    AI card issuing implementation typically takes three to nine months, depending on integration challenges, compliance, and vendor coordination. A precise implementation timeline also reflects user feedback cycles, testing requirements, customization depth, and system scalability considerations.

    Which Industries Benefit Most From Adaptive Spend Controls?

    Most notably, and with measured prudence, finance sectors, retail management, travel industry, tech startups, healthcare providers, and hospitality services benefit most from adaptive spend controls, where fluctuating expenses, distributed purchasing, and compliance sensitivities quietly demand tighter oversight.

    Can Small Businesses Afford Ai-Driven Card Programs?

    Yes, small businesses can often afford AI-driven card programs when cost analysis demonstrates efficiency gains outweigh fees. Adoption depends on budget constraints, transaction volume, vendor pricing, and whether automation meaningfully reduces administrative overhead and risk.

    How Do Employees React to Ai-Based Spending Decisions?

    Employees often react with mixed acceptance to AI-based spending decisions; employee perceptions improve when systems demonstrate spending transparency, consistent rationale, and fair exceptions, while opaque judgments, frequent overrides, or inflexible controls tend to generate distrust.

    What Training Do Finance Teams Need for AI Card Systems?

    Finance teams need training that gently illuminates AI card systems through data analysis, compliance training, and risk management, while strengthening team collaboration, guiding technology adoption, and refining user experience oversight for disciplined operational decision-making.

    Final words

    AI-driven card issuing is positioned to replace rigid spending rules with adaptive, data-informed controls that respond to context in real time. By combining machine learning, transaction intelligence, and disciplined guardrails, issuers can strengthen compliance, reduce friction, and improve employee access to approved funds. Program success will depend on measurable outcomes, resilient infrastructure, and transparent governance. As regulatory and operational demands expand, adaptive controls are likely to function like a compass, guiding spending with greater precision.